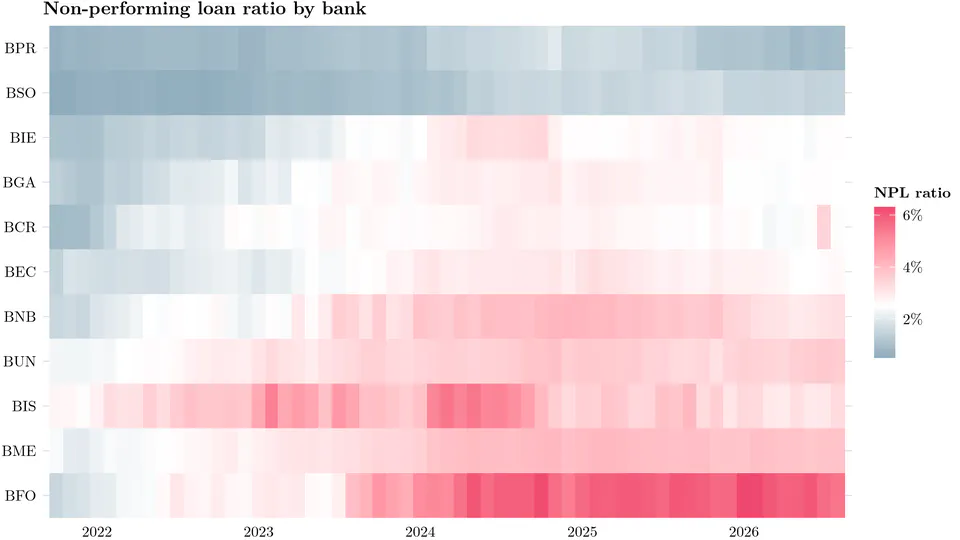
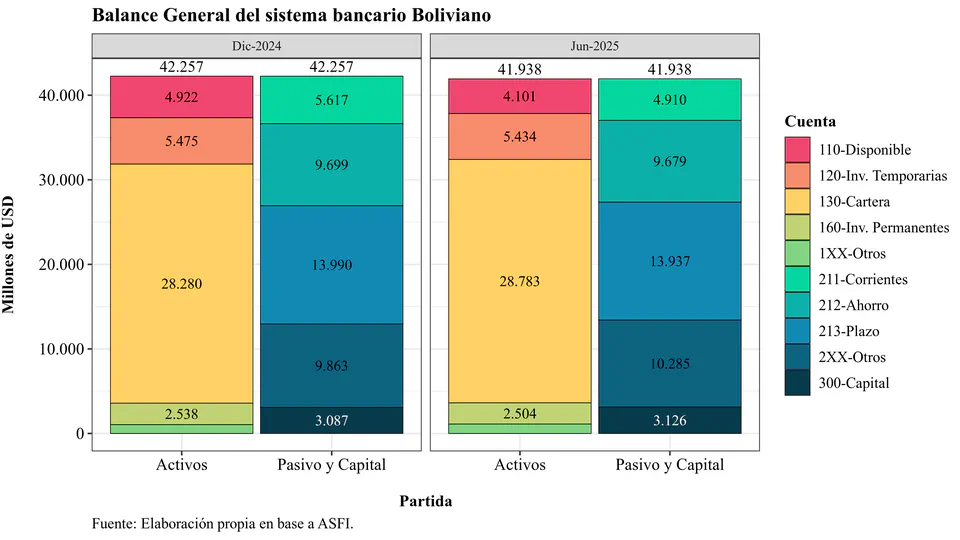
As of September 2026, Bolivia's banking system continues to record nominal balance-sheet growth of 11.6% year on year, driven primarily by long-term investments (+57.4%) and short-term investments (+36.5%), while cash and cash equivalents grew by 1.9%. By contrast, the loan portfolio increased by only 4.7%. The asset structure reveals a greater allocation of funds to instruments issued by the Central Bank of Bolivia and the public sector. On the funding side, current accounts (+20.3%), savings deposits (+24.3%), and term deposits (+12.2%) all increased, although the stronger growth of more liquid deposit instruments suggests a shift toward more volatile funding sources. The shares of foreign-currency assets and liabilities reached 9.3% and 9.6%, respectively, above the levels observed a year earlier. The non-performing loan ratio stood at 2.88% and continues to decline, although it remains above post-pandemic levels. Rescheduled loans, accounting for close to 15% of the total loan portfolio, remain a significant source of credit risk.
Are Bolivian Banks Solvent? The short answer is that they meet local regulatory requirements, but this does not exhaust the analysis. This post explains how the Capital Adequacy Ratio works, why the quality of capital matters, and how the way assets are weighted can change the interpretation of solvency. The case of BUN stands out because it combines the lowest CAP with the least regulatory density. The conclusion is that Bolivia should move towards a more internationally comparable prudential framework.
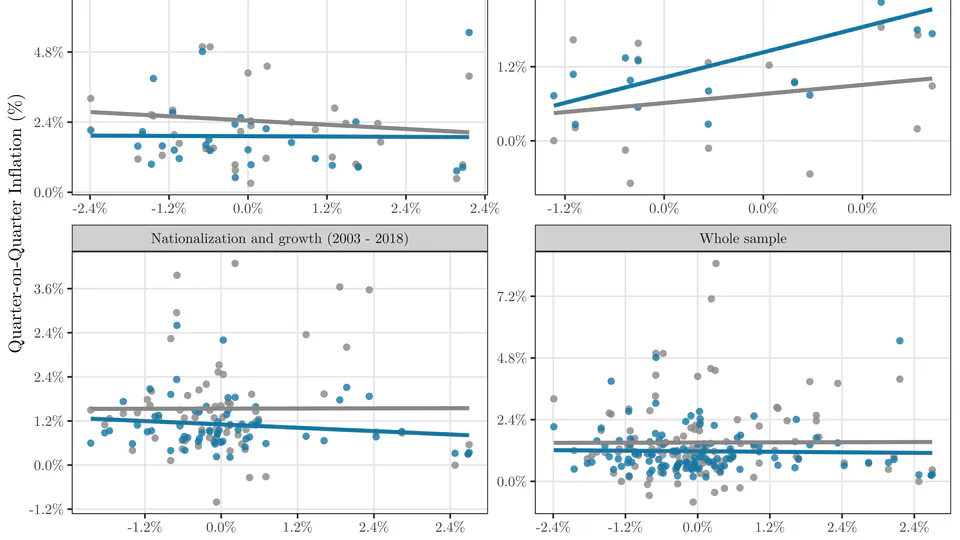
This paper estimates the relationship between inflation and the output gap at the departmental level in Bolivia, using quarterly data for the period 1993–2019. Despite substantial subnational variation, the association between inflation and economic slack is small and statistically indistinguishable from zero. This result holds across multiple specifications, including estimators that control for common factors and allow for regional heterogeneity. Even when separating tradable and non-tradable inflation, the relationship remains weak. The evidence suggests that inflation dynamics in Bolivia exhibit a strong common component and limited sensitivity to regional cyclical conditions, with important implications for understanding monetary policy transmission in a context of elevated inflation and institutional constraints.
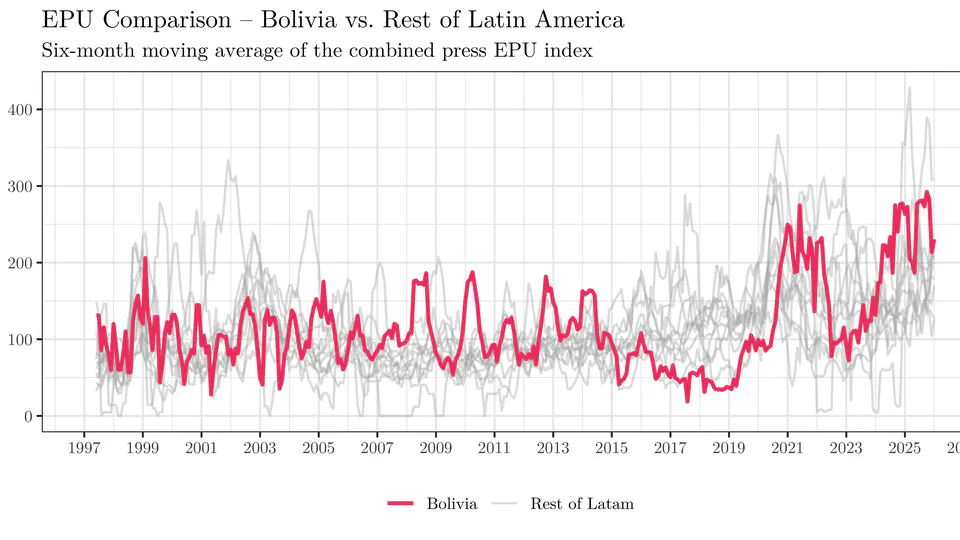
In this post I analyze the Economic Policy Uncertainty (EPU) Index recently published for Bolivia and other Latin American countries by the Bank of Spain. Using these data, I explore the recent evolution of economic uncertainty in Bolivia, its comparison with the rest of the region, and its possible relationship with recent political events. The results suggest that Bolivia remains among the countries with relatively high levels of uncertainty, reinforcing the importance of predictable economic policies and institutional frameworks based on clear rules. Reducing discretion in public policy can help strengthen economic confidence and create more favorable conditions for investment and growth.
As demand for reproducible macroeconomic analysis grows, manually extracting data from international organizations becomes a bottleneck: processes are poorly documented, non-scalable, and difficult to automate. SDMX —the statistical standard adopted by the IMF, ECB, OECD, World Bank, and others— offers a structured solution that makes it possible to find, understand, and extract data consistently through APIs. This post provides a practical introduction to how the SDMX model works, how to identify dataflows, structures, and codelists, and how to build reproducible queries in both XML and JSON. Using examples from the IMF (WEO) and the ECB (€STR), it shows a generalizable workflow for automating macroeconomic series in R, culminating with the use of the imfapi package, which abstracts much of the technical complexity.
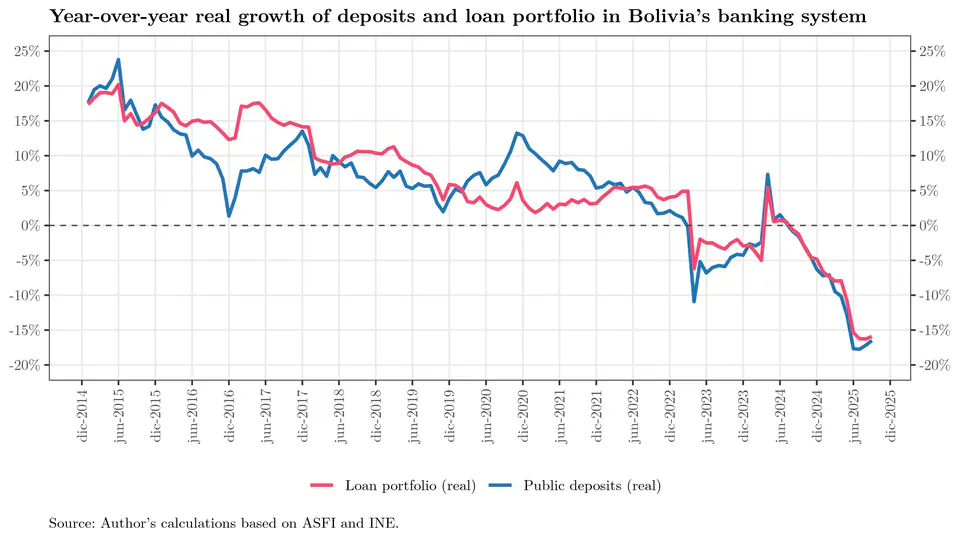
As of September 2025, the Bolivian banking system is operating in a defensive mode amid a fragile macroeconomic environment: the balance sheet expanded by +3.6% in nominal terms (≈ USD 1.479 billion at the official exchange rate), but credit and deposits contracted in real terms. Growth is concentrated in short-term liquid assets —cash and temporary investments— with greater exposure to the BCB and a rebound in account 124 (TGN), while loan portfolio growth has slowed. Funding has become more volatile, with a declining share of time deposits and increased reliance on savings and current accounts, in a context of USD scarcity and a “dual” exchange market. Asset quality remains under strain due to the reprogrammed portfolio (~15%), the main driver of non-performing loans. Despite a positive and recovering ROE, margins are under pressure (regulated lending rates and the need to raise deposit rates), reflecting reduced financial intermediation and growing dependence on the BCB for liquidity management.
This article shows how to extract economic data from the IMF using its DataMapper API, with `R` functions to organize and analyze information on indicators and countries. Applications are illustrated with Bolivia and Spain, demonstrating how to access structured data such as GDP growth, unemployment, inflation, fiscal balance, and public debt.
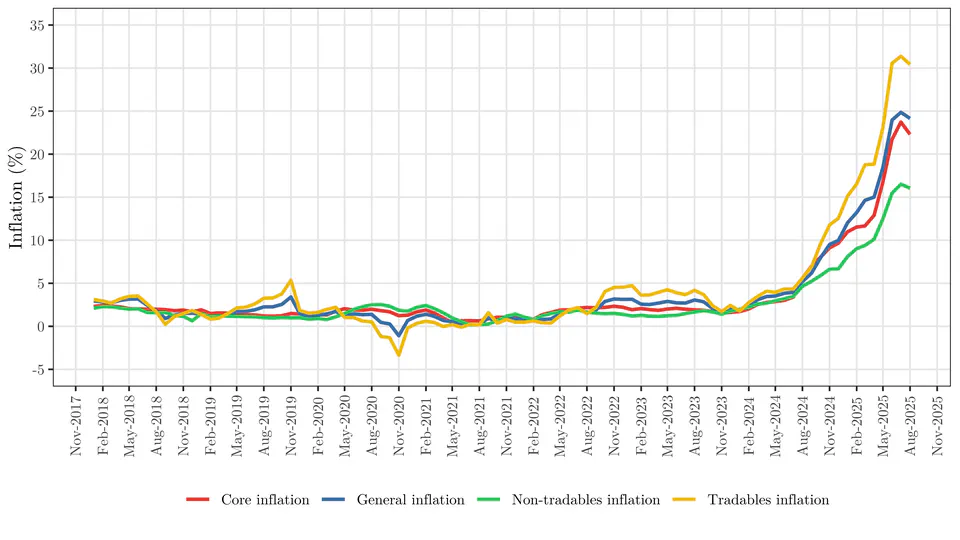
This article explores data extraction from ECLAC and its application to the analysis of inflation in Bolivia, using the R programming language to access relevant economic data. As of August 2025, Bolivia’s year-on-year inflation ranges from 16.05% (non-tradable goods) to 30.43% (tradable goods).
As of June 2025, the Bolivian banking system maintains a defensive strategy in response to a deteriorating macroeconomic environment. Balance sheet expansion is concentrated in temporary investments, mainly in instruments issued by the BCB and now also by the TGN, to the detriment of credit, whose growth is slowing and showing higher risk, especially in reprogrammed loans. Bank funding is becoming more volatile, with less reliance on term deposits and increasing dependence on savings and checking accounts. Although profitability is improving, it is doing so through low-risk, highly liquid assets, reflecting reduced financial intermediation and growing dependence on the BCB.
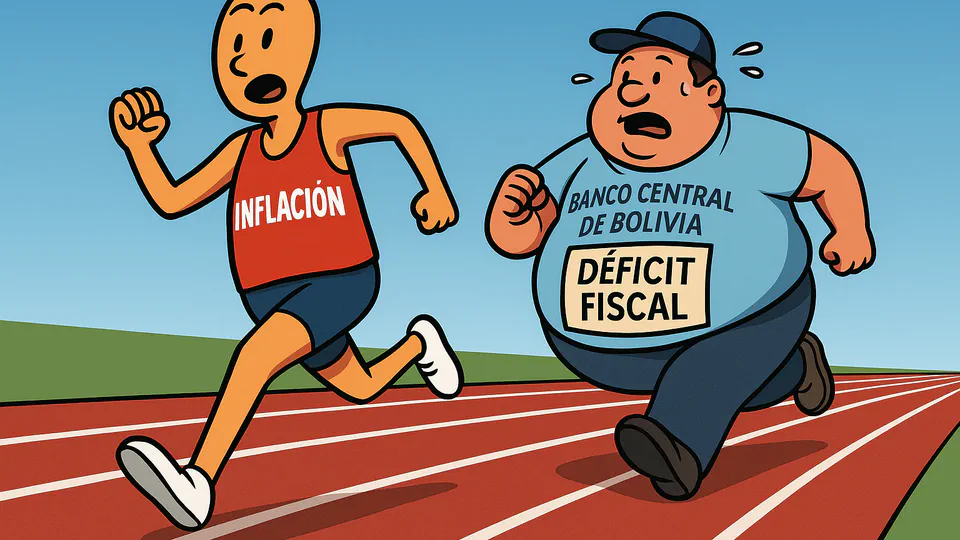
Since late 2023, Bolivia has been experiencing an accelerated and widespread inflationary process, with year-on-year inflation reaching 23.96% in June 2025 and sharp increases in both tradable goods —affected by the dual exchange rate— and non-tradables, as well zas core inflation. The persistent fiscal deficit, financed by the Central Bank through monetary issuance, has weakened the exchange rate regime, eroded institutional credibility, and limited the BCB's ability to control inflation. Without credible fiscal consolidation and the restoration of the Central Bank's autonomy, inflationary pressures will continue to intensify.